

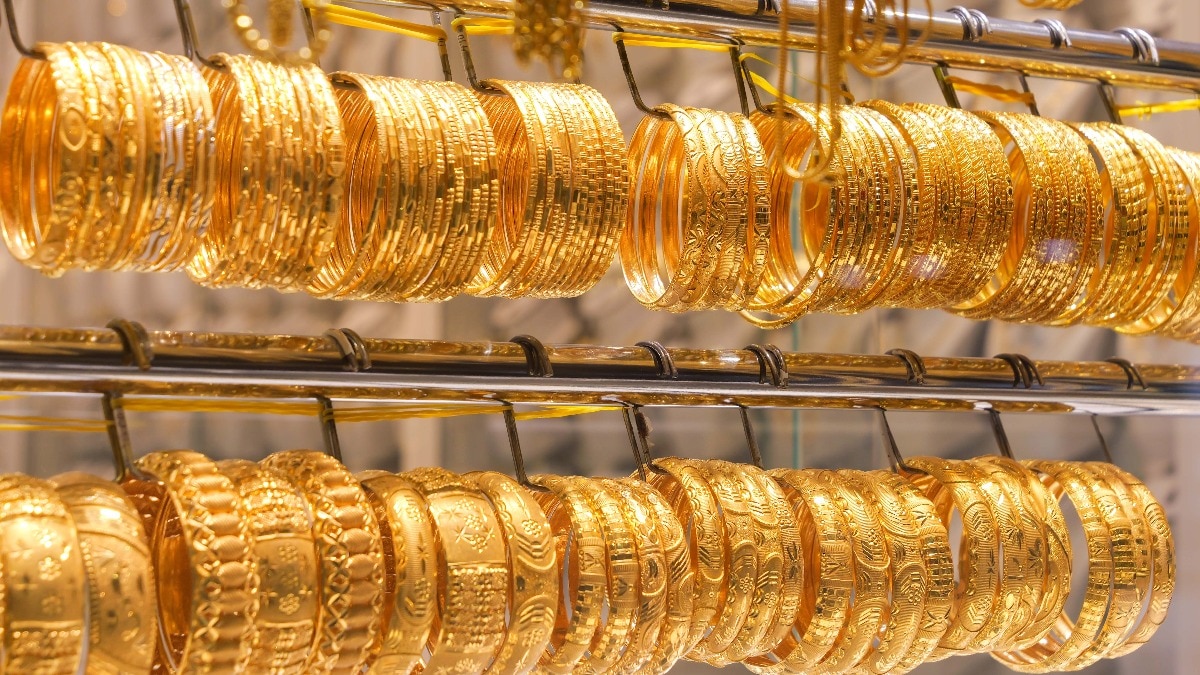
India experienced a steep decline in precious metal imports during September, with gold plunging by more than 81 percent and silver contracting nearly 49 percent compared to the same period a year earlier. Newly released figures from the Commerce Ministry highlight the sharp downturn, which coincides with broader government initiatives to protect foreign exchange reserves and navigate challenges stemming from the crisis in West Asia.
The dramatic reduction follows a decision by authorities to raise import duties on precious metals from 6 percent to 15 percent earlier in the year. This fiscal adjustment significantly increased the cost of acquiring foreign gold and silver, acting as a deterrent to overall domestic demand.
In tandem with these economic measures, Prime Minister Narendra Modi issued a public appeal encouraging citizens to postpone buying gold unless strictly necessary. The guidance was delivered against the backdrop of supply chain disruptions and escalating energy costs linked to the West Asia situation, as the government seeks to mitigate the broader economic fallout.
Because India relies heavily on overseas shipments to satisfy its domestic appetite for gold, high levels of importation routinely strain the national trade balance and foreign exchange reserves. Gold holds a central place in domestic cultural traditions, particularly during peak festive and wedding seasons, making demand management a critical factor for economic stability.
While curbing non-essential bullion purchases helps alleviate pressure on the import bill, future trends will ultimately be shaped by fluctuating international market prices, domestic consumer habits, and the persistence of regional geopolitical tensions.
Meanwhile, broader economic indicators for the month showed total merchandise imports reaching $74.61 billion, up from $69.08 billion in September of the previous year. Merchandise exports also registered notable growth, climbing to $44.40 billion from $36.08 billion, supported by robust performances in electronic goods, petroleum, engineering products, chemicals, and agricultural items.
In the services sector, imports expanded to $19.44 billion compared to $17.84 billion a year prior, while services exports experienced a slight contraction, moving down to $36.35 billion from $36.67 billion.